India’s solar manufacturing story has entered a new chapter.
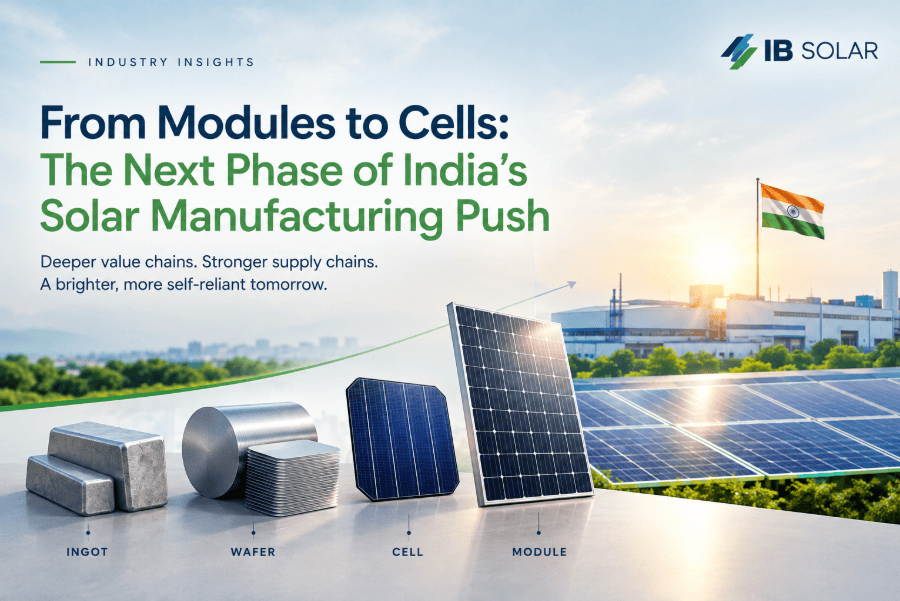
For years, the country’s manufacturing expansion was led by solar modules—the visible, final product assembled for deployment. But the next phase is moving deeper into the value chain: cells, wafers and ingots, the components that determine much of a module’s performance, cost and technological competitiveness.
The shift is already measurable. According to Mercom India, India’s cumulative module manufacturing capacity reached around 210 GW by December 2025, while solar cell manufacturing capacity stood at about 27 GW. (Mercomindia.com)
That gap explains why the conversation is changing.
The Cell Is the New Strategic Layer
A solar module may be the finished product, but the cell accounts for nearly 60% of module cost, according to the Council on Energy, Environment and Water (CEEW). (CEEW)
This makes cell manufacturing more than an import-substitution exercise. It is increasingly a question of value addition, technology ownership and supply-chain resilience.
India’s policy architecture reflects this transition.
The ALMM framework initially focused on modules. MNRE introduced ALMM List-II for solar cells in July 2025, with the framework requiring eligible projects to source cells from approved domestic manufacturers. The cell list has since been expanded repeatedly; by August 2026, enlisted cell capacity had reached 35.47 GW, according to MNRE data reported by Energetica India. (Ministry of New and Renewable Energy)
From Assembly to Integration
The government’s ₹24,000-crore Production Linked Incentive (PLI) scheme is designed to accelerate this evolution by encouraging high-efficiency manufacturing and integrated production.
Under Tranche-I, manufacturers were awarded capacity for 8.737 GW of fully integrated manufacturing. Tranche-II subsequently awarded 39.6 GW of fully or partially integrated manufacturing capacity. (Ministry of New and Renewable Energy)
The objective is significant: develop not merely more factories, but an ecosystem capable of producing increasingly sophisticated PV technology domestically.
And technology matters.
CEEW estimates that Indian solar-cell manufacturing currently costs nearly 40% more than Chinese production, while domestic manufacturers continue to face dependence on imported machinery, technical expertise and critical consumables. Its research also highlights the rapid transition from PERC towards TOPCon, underscoring the need for manufacturing capability that can keep pace with cell technology. (CEEW)
The Next Frontier: Wafers and Ingots
India’s manufacturing push is already moving further upstream.
In March 2026, MNRE proposed ALMM List-III for wafers, scheduled to become effective from 1 June 2028. The framework requires at least three independent wafer manufacturers with a combined capacity of 15 GW before the list can be issued; eligible wafer manufacturers must also have equivalent ingot-manufacturing capacity. (S3WaaS)
This is crucial because India’s module capacity has expanded far faster than upstream manufacturing. IEEFA estimates that by June 2026, module capacity had reached approximately 233 GW—nearly seven times cell capacity and 116 times ingot-wafer capacity. (IEEFA)
The message is clear: capacity alone is no longer the metric. Depth of manufacturing is.
What Comes Next
India has already built scale. The next challenge is to build technological depth, cost competitiveness and vertical integration.
With solar installations reaching 168.04 GW by August 2026, according to MNRE, the domestic market provides the demand foundation. (Ministry of New and Renewable Energy)
The next decade could therefore be defined not by how many modules India can assemble, but by how much of the solar value chain it can build at home—from ingot to wafer, wafer to cell, and cell to module.
India’s solar manufacturing story is moving upstream. And the cell is where that next chapter begins.